Market Overview: Defining the Home Appliances Glass Market scope
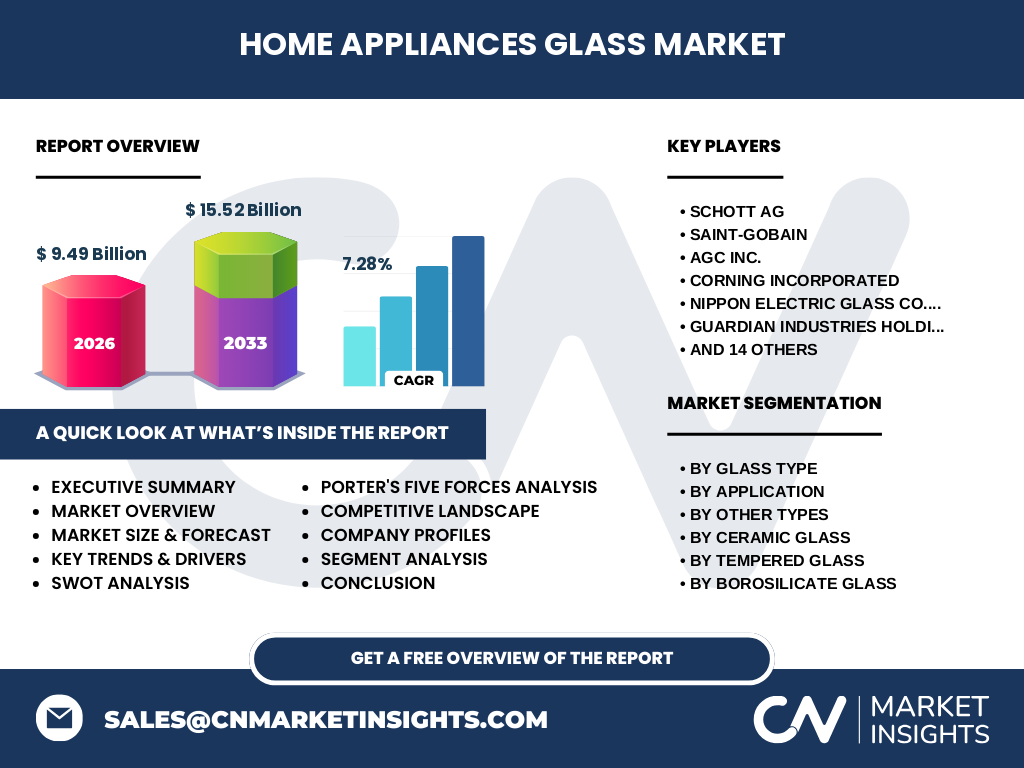
The Home Appliances Glass Market encompasses high-performance glass components engineered for durability and aesthetics in consumer electronics. Valued at 9.49 Billion in 2026, this sector focuses on tempered, borosilicate, and ceramic materials. Our analysis underscores its critical role in modern kitchen and laundry appliance design, where glass isn't just a surface—it is a functional interface for heat resistance and thermal safety.
What structural growth drivers and logistical hurdles shape this market?
Growth is primarily fueled by the premiumization of home appliances, requiring specialized Low-Iron Glass and Decorative Appliance Glass. However, firms like Schott AG and Saint-Gobain face logistical hurdles regarding energy-intensive production and global supply chain volatility. Our research indicates that navigating stringent ISO quality standards while managing port throughput in key hubs like Shanghai and Rotterdam remains a significant operational challenge for global manufacturers.
Emerging trends and long-term growth patterns
The market is shifting toward Smart Glass integration and enhanced sustainability. We observe a marked trend in Induction Cooktop Glass innovation, led by companies like EuroKera. As consumers demand higher safety and aesthetic continuity, the Home Appliances Glass Market is evolving to support integrated touch-sensitive panels, pushing manufacturers to prioritize high-temperature resistant panels that satisfy both electrical safety and sleek modern design requirements.
Impact of COVID-19 and recovery dynamics
Post-pandemic, the Home Appliances Glass Market experienced a rapid demand surge as home renovations became a priority. Despite initial supply chain bottlenecks, the industry proved resilient. Recovery is characterized by a rebound in the Washing Machine and Oven segments, as manufacturers aggressively optimized manufacturing processes to mitigate localized lockdowns, ensuring a stable trajectory toward our 2027-2033 forecast figures.
Competitive Benchmarking: Strategic dynamics of industry leaders
The landscape features high concentration among giants like AGC Inc., Corning Incorporated, and Nippon Electric Glass Co. Ltd. These players prioritize vertical integration and R&D for proprietary glass coatings. Fuyao Glass and Xinyi Glass emphasize cost-efficient scale, while Şişecam leverages strategic positioning to dominate regional supply lines, creating intense pressure on mid-tier players to differentiate through specialized borosilicate or ceramic technology.
Executive Summary: Synthesis of market health and outlook
Our analysis reveals a robust outlook for the Home Appliances Glass Market, with projections hitting 15.52 Billion by 2033 at a CAGR of 7.28%. The shift toward aesthetic, high-efficiency appliances acts as the primary catalyst. Successful firms are those effectively balancing the production of high-volume tempered glass with advanced, high-margin ceramic components for smart kitchen environments.
Projected growth trajectory from 2027 to 2033
From 2027 to 2033, the market is poised to grow from a 2026 baseline of 9.49 Billion to 15.52 Billion. This 7.28% CAGR is driven by accelerating replacement cycles in emerging economies and the increasing penetration of smart home appliances. We expect the highest growth in the Induction Cooktop Glass and Refrigerator component sectors as technical requirements for heat management become increasingly rigorous.
Detailed segmentation analysis of the appliance glass ecosystem
The market segments into: Glass Type (Tempered, Borosilicate, Ceramic, Low-Iron, Decorative); Application (Oven, Washing Machine, Refrigerators); and Distribution (Multi-Brand, Specialty, Online). Ceramic Glass, specifically for induction, commands a premium, whereas Tempered Glass remains the backbone of the refrigerator and oven door segments, providing essential safety and thermal expansion management in high-heat domestic environments.
Regional market performance and geographic distribution
The Home Appliances Glass Market exhibits strong concentration in the Asia-Pacific region, due to a dense cluster of manufacturing hubs like CSG Holding and Taiwan Glass. North America and Europe remain key demand centers for high-end, energy-efficient appliances. Our analysis shows that regional trade agreements and localized safety regulations heavily dictate the supply flow of raw materials for these distinct market clusters.
In-depth review of key regional market dynamics
China and Southeast Asia lead production volume, driven by proximity to major appliance assembly lines. Meanwhile, the European market, anchored by Schott AG, mandates stringent environmental certifications for glass production. The Americas show strong interest in Decorative Appliance Glass, where consumer preference for luxury, design-forward aesthetics forces a higher volume of investment in proprietary tempering and coating technologies compared to other regions.
Company Profiles and Strategic Positioning
Industry leaders like Vitro S.A.B. de C.V. and Asahi India Glass Limited are refining their footprints through localized production to bypass shipping volatility. Pilkington Group and Central Glass focus on thin-glass technology for smart interfaces. By aligning with specific appliance OEMs, these companies stabilize demand, effectively moving beyond mere commodity supply to become integral partners in the design-to-delivery lifecycle of global home appliance manufacturers.
Porter's Five Forces analysis of competitive intensity
The Home Appliances Glass Market features moderate-to-high rivalry among established players. While the threat of new entrants is low due to capital-intensive glass furnace requirements, the bargaining power of buyers is high, particularly for large appliance OEMs. Suppliers hold power through technological differentiation in ceramic and borosilicate performance, making high-quality, high-heat resistant glass a critical, non-substitutable resource for the industry's success.
SWOT Analysis: Strategic evaluation
Strengths include strong innovation in thermal management. Weaknesses involve high energy dependency in production. Opportunities lie in the proliferation of smart-home integrated glass panels and rapid expansion in emerging economies. Threats center on raw material cost volatility and stringent global environmental regulations, which could compress margins if manufacturers fail to adopt more efficient, low-emissions glass production technologies across their global facilities.
Value chain analysis from raw materials to end-users
The value chain starts with raw silica and additives, flowing to specialized manufacturers like Kibing Group and ILVA Glass for primary glass forming. Intermediate processes—tempering, coating, and precision cutting—add significant value before components reach appliance OEMs. The final distribution through Multi-Brand Stores and Online channels completes the cycle, where value is captured through the intersection of appliance functionality and consumer-facing aesthetic appeal.
Investment insights and high-potential growth areas
We identify Induction Cooktop Glass and Smart Interface Panels as high-potential areas for investors. Companies prioritizing sustainable, low-carbon manufacturing and advanced coatings are better positioned to capture market share in the premium segment. Strategic investments in Asian manufacturing hubs offer strong long-term yields, provided firms mitigate the risks of regional energy costs and supply chain disruptions through localized facility expansions.
Conclusion and key takeaways
The Home Appliances Glass Market is entering a high-growth phase toward 15.52 Billion by 2033. Success hinges on technological innovation in ceramic and borosilicate segments. Firms that successfully bridge the gap between high-performance safety requirements and modern, design-centric aesthetics will capture the majority of the market, benefiting from a sustained, global shift toward more sophisticated, connected home appliance ecosystems.
Research methodology: Ensuring data integrity
Our estimates are triangulated using a multi-layered approach: synthesizing trade registry data, primary interviews with procurement heads at major appliance OEMs, and secondary analysis of industrial output indices. We cross-reference production capacity from major players like AGC Inc. with regional import-export statistics to refine our market sizing, ensuring the 9.49 Billion 2026 baseline reflects accurate, actionable industry sentiment.
Scope of the report: Parameters and limitations
This analysis covers the global Home Appliances Glass Market, including tempered, borosilicate, and ceramic glass categories. It focuses on the industrial supply chain and appliance applications. While our 7.28% CAGR projection is robust, it assumes no major shifts in international trade law or catastrophic energy crises that could affect glass furnace operations globally. The scope excludes automotive or architectural glass sectors.
Recent developments and strategic market moves
Recent activity highlights a focus on joint ventures and production capacity expansion. Schott AG and EuroKera have made strategic pushes into high-tech cooking surfaces, while firms like Fuyao Glass are aggressively expanding their regional manufacturing footprint. These moves, combined with new product launches in smart-surface technology, demonstrate a proactive industry commitment to capturing the growing premium appliance demand identified in our 2027-2033 forecast.